Bookkeeping Basics
Bank Reconciliation Explained: A Simple Guide for Small Businesses
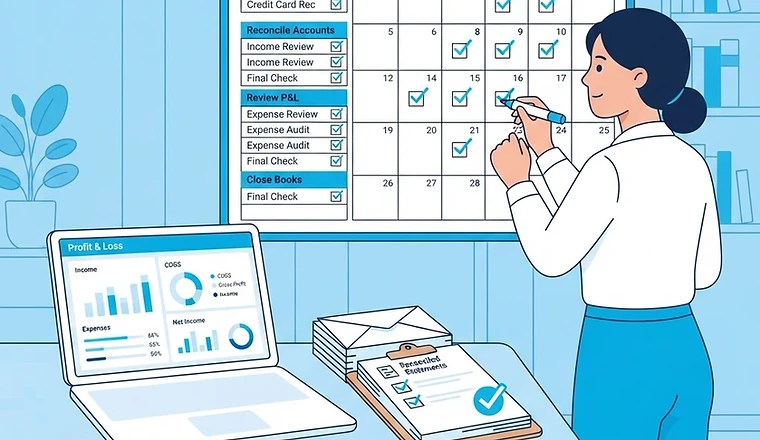
Quick answer
Bank reconciliation compares the transactions in your accounting software to your bank or card statement and confirms that the ending balances agree. You match each line, investigate differences such as timing items, duplicates or missing entries, and correct your books so the reconciled balance equals the statement balance.
Your accounting software shows a bank balance, and your bank shows one too. They will rarely match on their own. Reconciliation is how you find out why, and it is the step that makes the rest of your reports trustworthy.
What you need
- The bank or card statement for the period, with its closing balance.
- Your accounting file with transactions entered through the statement end date.
- The prior month's reconciled closing balance, which is this month's starting point.
How to reconcile, step by step
- 1Confirm the starting balance equals the prior statement's ending balance.
- 2Tick off each statement line that appears in your books for the same amount.
- 3List what is left on each side: items on the statement but not in the books, and items in the books but not on the statement.
- 4Enter missing items you can identify, and remove duplicates.
- 5Compare the reconciled ending balance with the statement balance. They should agree to the cent.
Differences that are normal
Timing differences are not errors. A check you wrote on the 29th may clear on the 3rd. A card payout may arrive a day after the sale. These stay as outstanding items until they clear, and they are why the reconciliation lists them separately.
Differences that are not
A difference that stays after timing items are accounted for points to a real problem: a transaction entered twice, a bank fee never recorded, a wrong amount, or a deposit posted to the wrong account. Do not plug the difference with an adjusting entry to make it match. Find the cause.
Credit cards, loans and payment processors
Reconcile every account that holds money or debt, not only the main checking account. Card statements and processor payouts are where personal spending and fees often hide. Sellers using Stripe, Shopify or marketplaces should also see our ecommerce bookkeeping guide.
How often to do it
Monthly is the usual minimum, at the same time as your month-end review. Busy accounts may deserve a weekly check. Our monthly close checklist shows where reconciliation fits in the close.
Doing it in QuickBooks or Xero
A short checklist for a clean reconciliation
Start with the statement ending balance, not the balance in your software. Confirm the beginning balance matches the prior month. Then match each transaction, clear only items that appear on the statement, and investigate anything that remains. When the difference is zero, save or print the reconciliation report so there is a record of the date and who completed it.
If the difference is not zero, do not force it with an adjusting entry. Look first for a transposed number, a duplicate, a missing deposit or a transaction posted in the wrong month. Differences are usually small mistakes that are easy to find once you look for them one by one.
Both tools have a reconciliation screen that walks you through the steps and shows the difference as you go. If the books have fallen behind, see our catch-up bookkeeping guide. To have it done for you, look at our QuickBooks bookkeeping services or get in touch.
Frequently asked questions
Is reconciling the same as categorizing transactions?
No. Categorizing decides where a transaction belongs in your reports. Reconciling proves the account balance agrees with the bank. You need both.
What if the difference is only a few dollars?
Still find it. Small differences are often a sign of a bank fee or interest entry that was never recorded, and they can hide larger errors.
Can I reconcile from the bank feed alone?
The feed helps, but the statement is the check. A feed can miss, duplicate or reorder transactions.
How long does a monthly reconciliation take?
For a small account with clean books, often under an hour. It takes longer when months were skipped or transactions are uncategorized.
Keep reading
Monthly Bookkeeping
What Does a Bookkeeper Do Each Month? A Small Business Owner's Guide
Each month, a bookkeeper records transactions, reconciles accounts, checks invoices and payroll, and prepares your reports. Here is exactly what should happen every month — and what you should receive.

Bookkeeping Basics
A Small Business Owner’s Guide to Monthly Bookkeeping
What monthly bookkeeping really involves, why it matters, and how to make it painless — even if you’d rather do literally anything else with your time.
Bookkeeping Basics
Catch-Up Bookkeeping: How to Fix Months of Neglected Books
Falling behind on your books is common. Catching up is a process with a clear order: gather statements, reconcile each account, fix what does not match, then lock the months so they stay fixed.
Written by
Moshe
Senior Account Manager, Mispar
Moshe is a Senior Account Manager at Mispar who works directly with small business owners and freelancers to keep their books clean, reconciled, and tax-ready every month.
More about Mispar